What to Ask Before You Buy an Indexed Annuity | Sheryl J. Moore
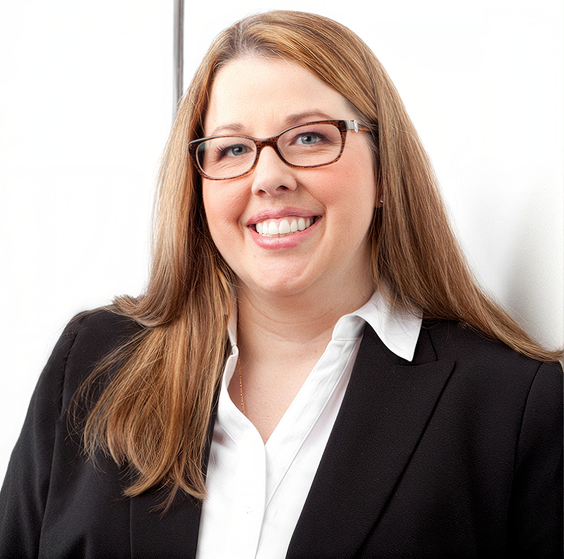
Sheryl J. Moore joins Brett A. Blake on Safe Money Radio for a walk through what she checks before buying an indexed annuity. Moore tells the story of her own 401(k) turning into a "201(k)" during the dot-com bust, and the conversation with her boss that led her to buy her first indexed annuity at age 29. She explains why the financial strength of the insurance company is her first shopping question, how risk pooling makes guaranteed lifetime income possible, and what to expect from an indexed annuity in real numbers. She also covers how an income rider differs from annuitization, why some firms avoid annuities, and why realistic expectations matter. Products discussed may not be suitable for everyone and are subject to state availability and individual suitability.
Loved this episode? Leave a review on Spotify or YouTube. It helps other listeners find the show.
Visit SafeMoneyRadio.com for every episode, and run your own numbers at brettblake.annuity.com.Safe Money Radio Show:Website | YouTube | Spotify | Facebook | Instagram | TikTok | X | LinkedIn
Brett Blake:LinkedIn | Retirement Tools | Email
Guest Sheryl J. Moore:Website | LinkedIn | Wink, Inc.
DISCLAIMER
Safe Money Radio is for educational purposes only and does not constitute investment, tax, or legal advice. Products discussed may not be appropriate for everyone. Guarantees are backed solely by the claims-paying ability of the issuing insurance company. Guarantees are not government-backed or provided by Annuity.com, Inc. All annuity products are subject to state availability and individual suitability. Brett A. Blake is a licensed insurance agent (NPN 21086345; CA License 6013124, operating as Annuity.com Insurance Marketing; NY License LA-1860109, operating as Annuity.com Insurance Solutions) and may be compensated by commission if a listener purchases an annuity through him. Brett is not a CPA, tax attorney, or registered investment advisor. By reaching out through any Safe Money Radio channel or the WIYN calculator, listeners consent to be contacted by a licensed insurance agent regarding annuity products.
GUEST DISCLOSURE:
Sheryl J. Moore is President & CEO of Moore Market Intelligence and Founder & CEO of Wink, Inc. She is a licensed insurance agent who does not sell insurance products and does not endorse any specific company or product. She is not a CPA or tax attorney. Statements and figures attributed to Ms. Moore in this episode reflect her own on-air statements. Ms. Moore did not compensate Safe Money Radio, Brett A. Blake, or Annuity.com, Inc. for her appearance, nor did she receive compensation for appearing.
What to Ask Before You Buy an Indexed Annuity
Moore's short answer to this week's question: check the financial strength of the insurance company first. Everything else, including the rate, comes after. In this week's episode of Safe Money Radio, host Brett A. Blake sits down with Sheryl J. Moore, President & CEO of Moore Market Intelligence and Founder & CEO of Wink, Inc., as she walks through what to check, how guaranteed lifetime income works, and how to set realistic expectations.
Financial Strength Comes First
Moore's first shopping question is not about the rate. It is about the insurance company. Every annuity contract, she says, states on page one or two that the guarantees in the contract are only as good as the claims-paying ability of the insurance company. In plain terms, if that company cannot pay, the paycheck stops.
That is why she starts with financial strength. Third-party firms like AM Best publish letter grades on insurance carriers. Moore reminds listeners that in the insurance world, a B rating is not the same as a B in high school. Higher-rated companies tend to be safer. Companies with lower ratings sometimes offer more competitive rates or higher payouts to attract business. Moore treats that as a caution flag, not a green light.
What Guaranty Associations Are
Moore mentions that state guaranty associations offer some protection if an insurance company becomes insolvent. She notes that this protection is not backed by the full faith and credit of the U.S. government, the way FDIC coverage is. She says most states protect up to $250,000 per contract, though limits vary by state.
She also says on air that she is aware of five annuity insurers since 2008 who have become insolvent, compared to more than 580 banks she says have failed in the same period. Those figures are her own.
This information is included here for consumer education only. State and federal rules prohibit using guaranty association coverage as a reason to buy an annuity. If you want to understand how the protection works in your state, ask a licensed professional.
Set Realistic Expectations
Moore is direct about what an indexed annuity actually does. She says if a fixed-rate annuity is crediting 5% today, an indexed annuity might earn 1% to 2% more than that over the life of the contract. In her words, nobody has ever complained about beating a CD.
She also says indexed annuities can produce occasional home runs. In her book, she publishes actual contract holder statements, and one shows a gain of 40% in a single year. She is clear: that is not the norm. If you buy expecting 40% every year, you will be disappointed. If you buy expecting something a little better than a CD, with no market losses to worry about, you have set the right expectation.
How Risk Pooling Pays Lifetime Income
Moore explains lifetime income through a concept called risk pooling. She is careful to say she is not an actuary and does not play one on TV. Here is the idea. When you buy certain types of annuities, if you die shortly after purchase, in some cases your beneficiaries may not get the money back. Those cases help fund the paychecks for people who live much longer than expected. Moore puts it plainly: it helps fund the retirement paychecks of people who live to be 122.
This is how insurance carriers can pay a lifetime income. The pool spreads the risk. People who live longest still get paid.
Income Rider vs. Annuitization
Moore helped develop the income rider concept for fixed and indexed annuities. Here is the difference.
Annuitization is the traditional way of turning on income. You tell the carrier you are ready, they calculate a payment, and you receive that same paycheck every month until you die. It is simple. It is also inflexible. You cannot take extra out. And in many cases, if you die shortly after starting payments, nobody else receives anything.
An income rider works differently. It still pays a paycheck for life. But if you get in a car accident and need an extra thousand dollars for a deductible, you can get to it. There may be penalties. It is possible. Moore adds that when an income rider is used, the full annuity value is payable to your loved ones on your death. She estimates roughly 98% of buyers choose an option where beneficiaries can access the full contract value.
Why Some Advisors Avoid Annuities
Not all financial services professionals sell annuities. Moore points out that many advisors at large brokerage firms do not care for annuities, and the reason is compensation. Firms that manage assets earn a fee on those assets year after year. Once your money moves into an annuity, that fee stream ends.
Annuity agents are usually paid a commission, one time, by the insurance company. That commission does not come out of the buyer's money in the way an ongoing management fee does. Some advisors will point to a 5% annuity commission and compare it unfavorably to their own 1% annual fee. Moore says that is not a fair comparison. The 5% is one time. The 1% is every year, for as long as the relationship continues.
Her point is not that one model is better. Her point is that if you want an annuity, ask directly: do you sell annuities? Do not assume your usual advisor covers this ground.
Suitability Rules Guide the Conversation
When you shop for an annuity, you may be asked personal questions. Your income. Your other assets. Your monthly expenses. That can feel intrusive. Moore says it is required. Suitability regulation dictates how much of a person's income or assets can go into an annuity, and the percentage is not the same for everyone. She says one person might qualify to place 70% of their money in an annuity, while another might cap out at 25%. It depends on the full picture.
FAQ
What is the number one question to ask before buying an indexed annuity? Moore says it is the financial strength of the insurance company. The rate matters less than the ability of the carrier to keep its promise.
Should I put all of my money into an annuity? No. Moore says most regulations would not allow it. Keep some money accessible for near-term needs.
Will an indexed annuity earn 10% every year? No. Moore says to expect roughly 1% to 2% more than a fixed-rate annuity over the life of the contract. Larger years happen. They are not the norm.
How is an income rider different from annuitization? Annuitization gives you a fixed paycheck for life with little flexibility. An income rider pays a lifetime income, keeps some of your annuity value available for withdrawals, and passes the full value to beneficiaries on death.
Where To Start
Want to take the next step? Run your own numbers with the free WIYN calculator at brettblake.annuity.com, which takes about three minutes. Ready to talk it through? Book a Retirement Clarity Session with Brett. No obligation, no pressure. Brett is a licensed insurance agent and may recommend an annuity if it fits.
Worry Less. Live Longer.
About the host
Brett A. Blake hosts Safe Money Radio and is a licensed insurance agent (NPN 21086345). He is 58 and working through the same retirement questions as his listeners. He jokes his Harvard MBA taught him almost nothing about retirement income. Brett helped build a business that started near $50 million and reached nearly $1 billion. Brett is not a CPA or tax attorney.
About the guest
Sheryl J. Moore is President & CEO of Moore Market Intelligence and Founder & CEO of Wink, Inc., based in Des Moines, Iowa. She has led at the Society of Annuity Facts and Education for over a decade, currently as Chief Research Officer. Her research has been presented to Congress. She wrote Why I Bought Indexed Annuities and co-wrote The Encyclopedia to Indexed Products. Not a CPA or tax attorney.
Safe Money Radio:
Website | YouTube | Spotify | Facebook | Instagram | TikTok | X | LinkedIn
Brett A. Blake:
LinkedIn | Retirement Tools | Email
Sheryl J. Moore:
Website | LinkedIn | Wink, Inc.
#SafeMoneyRadio #IndexedAnnuities #RetirementIncome #GuaranteedIncome #FinancialSecurity #WorryLessLiveLonger
DISCLAIMER: Safe Money Radio is for educational purposes only and does not constitute investment, tax, or legal advice. Products discussed may not be appropriate for everyone. Guarantees are backed solely by the claims-paying ability of the issuing insurance company. Guarantees are not government-backed or provided by Annuity.com, Inc. All annuity products are subject to state availability and individual suitability. Brett A. Blake is a licensed insurance agent (NPN 21086345; CA License 6013124, operating as Annuity.com Insurance Marketing; NY License LA-1860109, operating as Annuity.com Insurance Solutions) and may be compensated by commission if a listener purchases an annuity through him. Brett is not a CPA, tax attorney, or registered investment advisor. By reaching out through any Safe Money Radio channel or the WIYN calculator, listeners consent to be contacted by a licensed insurance agent regarding annuity products.
GUEST DISCLOSURE:
Sheryl J. Moore is President & CEO of Moore Market Intelligence and Founder & CEO of Wink, Inc. She is a licensed insurance agent who does not sell insurance products and does not endorse any specific company or product. She is not a CPA or tax attorney. Statements and figures attributed to Ms. Moore in this episode reflect her own on-air statements. Ms. Moore did not compensate Safe Money Radio, Brett A. Blake, or Annuity.com, Inc. for her appearance, nor did she receive compensation for appearing.